Umbrella Insurance $1M: Protect Your Investments
Advertisements
Umbrella insurance for investment portfolio protection provides an additional layer of personal liability coverage that may help investors manage the financial consequences of major lawsuits. Learn how a $1 million policy works, which claims may be covered, what exclusions to review, and how to determine whether the coverage fits your financial situation.
Umbrella insurance for investment portfolio protection is an important consideration for Americans who want to manage personal liability risks while preserving their long-term financial goals.
A serious accident or covered liability claim can create financial obligations that exceed the limits of ordinary homeowners or auto insurance.
Understanding how a $1 million umbrella policy works can help investors evaluate their exposure, compare available coverage, and make more informed decisions about protecting accumulated assets.
Why Additional Liability Protection Matters for Investors
Building a diversified investment portfolio often requires years of saving, financial discipline, and carefully considered decisions.
However, investment performance is not the only factor that can affect personal wealth. Legal liabilities arising from accidents or other covered incidents may also have financial consequences.
For this reason, umbrella insurance for investment portfolio protection can complement broader financial strategies by offering additional liability coverage when qualifying claims exceed existing policy limits.
Understanding Personal Liability Exposure
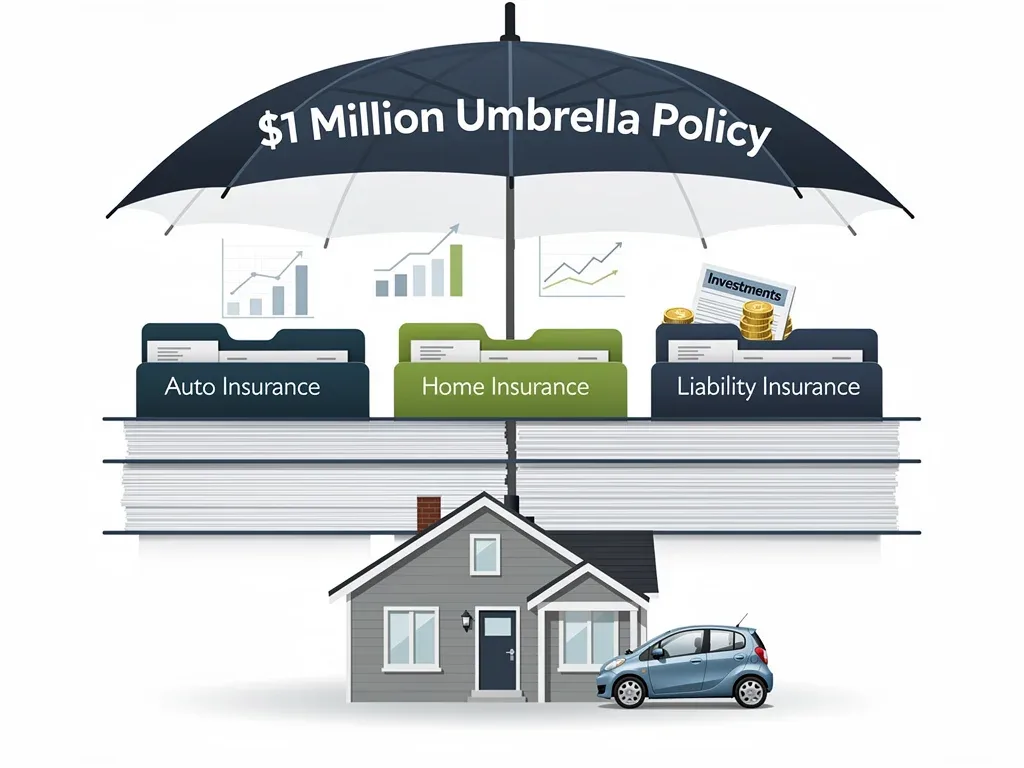
Personal liability refers to situations in which an individual may be legally responsible for injury to another person or damage to someone else's property.
Examples can include an automobile collision, an accident involving a visitor on private property, or other incidents covered under an applicable insurance contract.
Although standard insurance policies provide important protection, their liability limits may not be sufficient for every serious claim.
Why Insurance Belongs in Financial Planning
Investors often focus on diversification, retirement accounts, emergency savings, and asset allocation when developing long-term financial plans.
Liability insurance addresses a different category of financial risk because it may help pay qualifying legal judgments, settlements, and defense expenses.
Combining appropriate insurance with responsible financial planning can create a more comprehensive approach to managing potential losses.
Understanding Umbrella Insurance Policies
Personal umbrella insurance generally provides additional liability protection beyond the limits of qualifying underlying insurance policies.
These underlying policies may include homeowners, renters, automobile, or other eligible personal liability insurance, depending on the insurer's requirements.
The role of umbrella insurance for investment portfolio protection is to reduce potential out-of-pocket liability expenses for covered claims, not to insure the investments themselves against market losses.
What $1 Million in Umbrella Coverage Means
A $1 million umbrella policy generally provides up to $1 million in additional liability protection under the terms of the contract.
For a qualifying claim, the underlying insurance policy typically responds first, and the umbrella policy may cover eligible amounts above the required underlying limit.
However, coverage depends on exclusions, policy conditions, applicable limits, and whether the incident falls within the insurer's definition of a covered claim.
How Umbrella Insurance Differs From Regular Insurance
Homeowners insurance commonly includes liability coverage for certain incidents involving other people or their property.
Automobile insurance can provide liability protection when an insured driver is legally responsible for a covered accident.
An umbrella policy generally supplements these protections, although some contracts may also cover certain personal liability situations not included in the underlying insurance.
What Umbrella Insurance Does Not Protect
Umbrella insurance is not designed to reimburse investors for declining stock prices, unsuccessful business investments, or ordinary market volatility.
It also generally does not cover damage to the policyholder's own property or many liabilities associated with intentional wrongdoing, business activities, or certain contractual obligations.
Anyone considering umbrella insurance for investment portfolio protection should review the specific exclusions rather than assuming that every potential financial loss will qualify.
Why Investment Portfolios May Be Exposed to Liability Judgments
Personal investments can represent a substantial portion of an individual's financial resources, particularly after years of consistent saving.
When a person faces a legal obligation that is not fully covered by insurance, certain personal assets may become relevant to satisfying an enforceable judgment.
However, asset protection rules vary by state and account type, meaning some retirement assets and other property may receive legal protections that do not apply equally to ordinary brokerage accounts.
Investment Accounts and Personal Asset Protection
Taxable brokerage accounts, savings, real estate, and other holdings can contribute to an individual's overall net worth.
Depending on applicable law, some assets may be exposed to collection proceedings if a court enters a judgment that exceeds available insurance protection.
Appropriate umbrella insurance for investment portfolio protection may reduce this exposure for covered claims, but it cannot guarantee that every asset will remain untouched.
Common Scenarios That Can Create Major Liability
Some everyday activities create potential liability risks even when individuals follow reasonable safety precautions.
Severe injuries, extensive property damage, and disputes involving personal conduct can result in claims that require substantial financial resources.
Understanding these situations allows investors to evaluate whether their existing liability coverage is appropriate for their circumstances.
Automobile Accidents: Serious collisions may involve medical expenses, property damage, and lost income.
Property Injuries: Certain accidents involving visitors can create liability for homeowners.
Personal Injury Claims: Some policies cover specified claims involving libel, slander, or related allegations.
Teenage Drivers: Adding inexperienced drivers may change a household's overall risk exposure.
Rental Properties: Rental activities may require additional coverage or specialized insurance arrangements.
How Umbrella Insurance Works With Existing Policies
Umbrella insurance generally operates alongside primary liability policies rather than replacing them.
Insurance companies commonly require policyholders to maintain specified minimum liability limits on their underlying coverage.
These requirements are essential when evaluating umbrella insurance for investment portfolio protection, because inadequate underlying insurance may affect eligibility or create uncovered financial obligations.
Understanding the Layers of Liability Coverage
Imagine an automobile insurance policy with a qualifying liability limit of $500,000 and an additional $1 million personal umbrella policy.
If a covered claim results in $1.2 million of eligible liability, the underlying policy might pay $500,000, while the umbrella policy could respond to the remaining $700,000.
This simplified example assumes the applicable limits, policy conditions, and coverage requirements are satisfied, and that no exclusions or other restrictions apply.
Why Underlying Insurance Limits Matter
Insurers frequently establish minimum homeowners and automobile liability limits that must be maintained before umbrella coverage becomes available.
A policyholder who fails to maintain those limits may face a financial gap, even when the umbrella policy remains in force.
Reviewing both the primary insurance contracts and the umbrella policy is therefore important for understanding the combined protection.
Legal Defense Costs and Policy Conditions
Some personal umbrella policies provide legal defense services for qualifying claims, potentially helping with attorney expenses and litigation costs.
However, the treatment of defense costs differs between policies, including whether those costs reduce the available coverage limit.
Investors should verify how their insurer handles legal representation, claim reporting, settlements, and defense expenses before selecting a policy.
Evaluating Your Personal Liability Exposure
The appropriate amount of umbrella coverage depends on more than the value of an investment portfolio.
Household circumstances, existing insurance limits, personal activities, real estate ownership, and potential legal exposures can all influence coverage needs.
For investors, selecting umbrella insurance for investment portfolio protection should involve a broader assessment of financial risk rather than automatically choosing the lowest available limit.
Factors That May Affect Coverage Needs
Individuals with several properties, vehicles, or activities associated with higher liability exposure may need to examine their insurance requirements more carefully.
A household with significant savings but relatively limited liability exposure may have different priorities from a household with multiple drivers and rental properties.
These differences make personalized evaluation more useful than relying on a universal recommendation based only on net worth.
Net Worth: Consider the value and legal characteristics of personal assets.
Existing Coverage: Review liability limits and exclusions in current policies.
Household Drivers: Account for the number and experience of insured drivers.
Property Ownership: Evaluate residences, rentals, pools, and other relevant exposures.
Personal Activities: Consider circumstances that may create additional liability risks.
Is $1 Million Enough for Every Investor?
A $1 million personal umbrella policy is a common starting point because many insurers offer coverage in million-dollar increments.
However, there is no universal rule establishing that every investor requires exactly $1 million or that coverage must always equal net worth.
Some households may need higher limits, while others may find that increasing underlying liability coverage is a more appropriate initial step.
Understanding State Asset Protection Rules
State laws and federal provisions can affect whether particular assets are protected from certain creditors or legal judgments.
Retirement accounts, homestead interests, and other property may receive different treatment depending on the circumstances.
Because umbrella insurance for investment portfolio protection does not replace legal asset protection planning, investors with complex holdings may benefit from consulting an attorney familiar with their state's laws.
The Cost of $1 Million in Umbrella Insurance
Personal umbrella insurance is often considered relatively affordable compared with the additional liability limit it provides.
Nevertheless, the annual premium depends on the insurer, the amount of coverage, the household's risk factors, and the required underlying insurance.
Comparing personalized quotes is more reliable than assuming that every $1 million umbrella policy will cost the same amount.
Factors That Influence Insurance Premiums
Insurance providers may consider the number of vehicles, drivers, properties, and other household risk characteristics when calculating premiums.
Driving history, the presence of young drivers, and specific recreational or property-related exposures may also influence eligibility and cost.
For this reason, umbrella insurance for investment portfolio protection should be evaluated using current quotes rather than an assumed universal annual price.
Understanding the Total Insurance Cost
The umbrella policy's premium is not necessarily the only expense associated with obtaining additional liability protection.
An insurer may require higher liability limits on existing homeowners or automobile policies before offering umbrella coverage.
Consumers should therefore compare the combined cost of all required coverage, including any adjustments to their primary insurance contracts.
Comparing Price and Coverage Quality
A lower premium does not automatically indicate better value if the policy includes exclusions that affect important household risks.
Likewise, a higher price does not guarantee broader coverage unless the additional protections appear in the contract.
The most useful comparison considers the liability limits, defense provisions, exclusions, underlying requirements, and total annual expense.
Long-Term Financial Security and Asset Preservation
Investors often build portfolios to support retirement, education expenses, housing goals, or long-term financial independence.
Unexpected legal obligations can interfere with those plans, especially when financial exposure exceeds available liability insurance.
Appropriate umbrella insurance for investment portfolio protection can help manage covered risks while allowing other financial planning strategies to address different kinds of uncertainty.
How Liability Coverage Supports Retirement Planning
Retirement planning usually involves estimating future expenses, investment income, and the level of savings required to maintain financial stability.
Liability insurance may help protect some of those plans from the consequences of qualifying accidents and lawsuits.
However, policy limits still apply, and insurance cannot eliminate every financial risk or guarantee that accumulated investments will remain unaffected.
Why Diversification Is Not the Same as Liability Protection
Investment diversification is designed to manage exposure across different assets, sectors, and market conditions.
Umbrella insurance serves another purpose by addressing specified personal liability risks that may arise outside the investment portfolio.
Investors can explore additional risk management strategies while recognizing that insurance and diversification solve different financial problems.
Integrating Umbrella Insurance Into Your Financial Plan
Adding an umbrella policy should involve reviewing the insurance coverage already in place and identifying meaningful gaps.
Consumers can compare available policies, estimate potential liability exposure, and confirm whether minimum underlying coverage requirements are satisfied.
This process helps make umbrella insurance for investment portfolio protection part of a broader financial plan rather than an isolated purchase.
Steps for Evaluating Your Coverage
Start by reviewing the liability limits and declarations pages of existing homeowners, renters, automobile, or other relevant insurance policies.
Next, consider household characteristics that could influence potential liability exposure and request comparable umbrella insurance quotes.
Finally, review the full policy language before purchasing, paying particular attention to exclusions, covered individuals, applicable limits, and required primary coverage.
Review Existing Policies: Identify current liability limits and possible gaps.
Assess Personal Exposure: Consider household drivers, properties, and activities.
Compare Quotes: Evaluate both premiums and policy conditions.
Check Exclusions: Confirm whether important liability scenarios are covered.
Review Regularly: Reassess coverage after major financial or lifestyle changes.
Questions to Ask an Insurance Professional
Before selecting a policy, ask which underlying insurance limits must be maintained and whether every household member or property is included.
Clarify how the insurer handles claims involving rental properties, personal injury allegations, recreational vehicles, or other relevant exposures.
Also ask whether defense expenses reduce the policy limit and whether any self-insured retention applies to particular claims.
When to Reevaluate Your Umbrella Coverage
Insurance needs can change as individuals acquire additional property, build investment assets, or make important household decisions.
Adding a teenage driver, purchasing a rental property, or changing insurers may justify reviewing the terms of existing coverage.
A periodic review can help ensure that umbrella insurance for investment portfolio protection remains appropriate for the household's current circumstances.
Common Mistakes When Purchasing Umbrella Insurance
Some consumers assume that every umbrella policy provides identical protection because coverage limits are commonly advertised in similar amounts.
In reality, policies can differ in exclusions, covered activities, underlying requirements, and the handling of legal defense costs.
Understanding these differences can help investors avoid purchasing a policy that does not address their most relevant personal liability exposures.
Assuming All Lawsuits Are Covered
Umbrella insurance is generally intended for qualifying personal liability claims rather than every possible lawsuit.
Claims involving business operations, intentional conduct, professional activities, or contractual disputes may require different coverage.
Investors should not assume that a $1 million umbrella policy automatically protects them from litigation involving investment advice or business-related decisions.
Choosing Coverage Based Only on Net Worth
Net worth can be relevant when evaluating potential financial exposure, but it is not the only consideration.
Different assets may receive different legal protections, and household activities may increase or reduce the likelihood of certain liability claims.
A more complete assessment considers both the nature of the potential risks and the financial resources available to respond to them.
Ignoring Policy Exclusions and Requirements
Failure to understand coverage exclusions may create unrealistic expectations when a claim occurs.
Similarly, not maintaining required underlying insurance limits can lead to complications or uncovered expenses.
Carefully reading the policy and discussing unclear terms with the insurer can help prevent avoidable misunderstandings.
Recent Trends and the Future of Liability Protection
Medical expenses, legal costs, and the financial consequences of serious accidents remain important considerations in personal liability planning.
However, the value of umbrella insurance should not depend on unsupported predictions that every lawsuit will produce increasingly large judgments.
For investors considering umbrella insurance for investment portfolio protection, it is more useful to focus on their actual exposures and the protections specified by available policies.
Changes in Household Risk Profiles
Household risks may evolve when individuals acquire new properties, change driving habits, or expand their personal activities.
Insurance products and underwriting practices may also change as providers reassess costs and eligibility requirements.
Reviewing current policy options can help consumers determine whether their existing liability limits remain appropriate.
What Investors Should Monitor
Investors should periodically examine their insurance contracts alongside major changes in assets, household responsibilities, and financial goals.
Comparing quotations and reviewing relevant state insurance guidance can provide additional information about available protections.
Professional advice may be particularly valuable when substantial assets, rental properties, or business activities create complicated liability considerations.
Umbrella Insurance Protection at a Glance
The following summary highlights important features of personal umbrella coverage and their relevance to financial planning.
These characteristics describe general insurance principles rather than the terms of any particular contract.
Before purchasing umbrella insurance for investment portfolio protection, consumers should confirm the actual limits, requirements, and exclusions offered by their insurer.
Key Point | Brief Description |
|---|---|
Extended Coverage | May provide additional personal liability protection beyond qualifying underlying insurance limits. |
Asset Protection | Can help reduce the financial impact of covered liability judgments, subject to policy conditions. |
Cost Considerations | Premiums depend on coverage limits, household risk factors, location, and required underlying insurance. |
Financial Planning | Offers an additional risk management tool alongside investment planning and other insurance coverage. |
Frequently Asked Questions About Umbrella Insurance
What is an umbrella insurance policy?▼
A personal umbrella insurance policy generally provides additional liability protection beyond the limits of qualifying homeowners, automobile, or other underlying insurance. Depending on the contract, it may also cover certain liability claims that primary policies do not. Coverage is subject to exclusions, conditions, and the limits stated in the policy.
Why is $1 million coverage recommended for investors?▼
One million dollars is a common starting coverage amount because personal umbrella insurance is frequently offered in million-dollar increments. It can provide meaningful additional protection for eligible claims, but it is not automatically sufficient for every investor. Appropriate limits depend on household risks, financial exposure, other insurance coverage, and personal circumstances.
What types of claims does umbrella insurance cover?▼
Umbrella insurance may cover specified bodily injury, property damage, and personal injury liability claims. Depending on the policy, protection can extend to certain allegations involving libel or slander and may include legal defense costs. Business liabilities, intentional wrongdoing, and other excluded activities may not be covered, so reviewing the contract is essential.
How does umbrella insurance protect investment portfolios?▼
If an insured person becomes legally responsible for a covered claim exceeding applicable primary liability limits, an umbrella policy may pay additional eligible amounts up to its own limit. This can reduce the need to use personal financial resources, potentially including investments. However, it does not guarantee that all assets are protected from every judgment or lawsuit.
Is umbrella insurance expensive?▼
A $1 million personal umbrella policy often costs a few hundred dollars annually, but premiums vary considerably. Location, household drivers, properties, claims history, coverage limits, and insurer requirements can affect the price. Consumers may also need to increase their underlying insurance limits, adding to the total cost. Personalized quotes provide the most reliable estimate.
What Umbrella Insurance Means for Long-Term Investors
Umbrella insurance for investment portfolio protection can be a useful component of personal financial planning because it addresses certain liability risks that investment diversification alone cannot manage.
A $1 million policy may offer substantial additional coverage for qualifying claims, but its effectiveness depends on the contract, underlying insurance, exclusions, and individual circumstances.
For investors focused on long-term financial stability, the most appropriate approach is to evaluate existing protections, understand potential liability exposure, and select coverage that fits their overall risk management strategy.